The 50/30/20 Budget: Why It Works and How to Customize It for Your Life
A simple rule for splitting after-tax income into needs, wants, and savings—and how to bend it without breaking it.
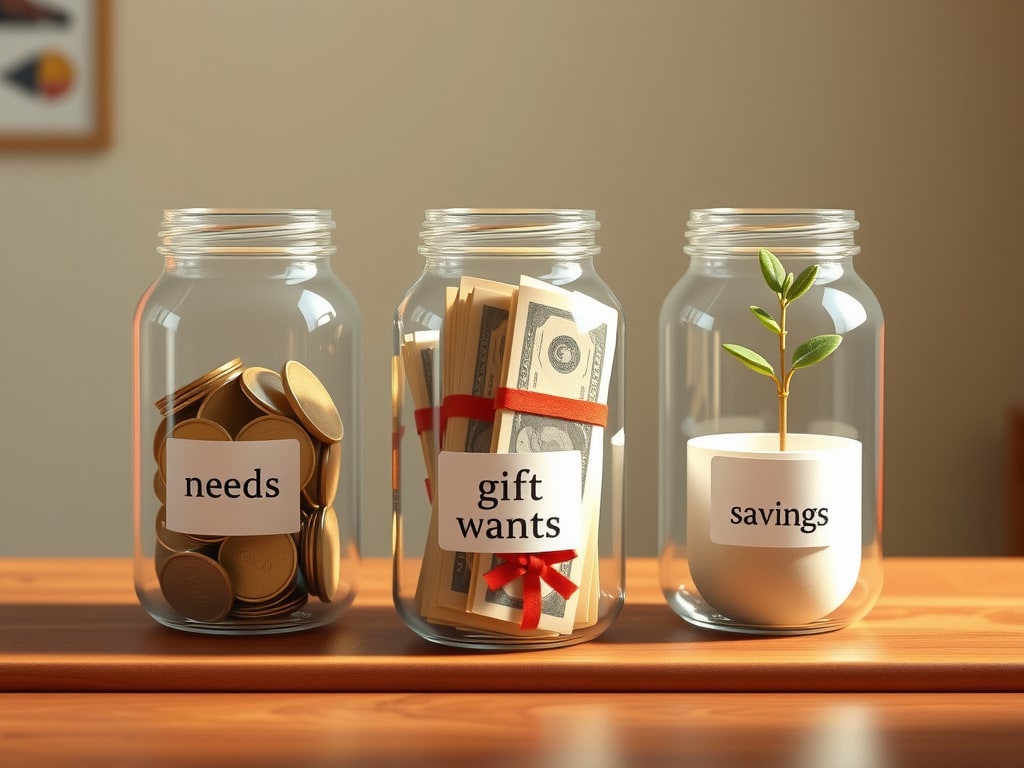
Elizabeth Warren didn't invent the idea of spending less than you earn, but the U.S. senator from Massachusetts did popularize a simple way to do it: the 50/30/20 budget. In her book 'All Your Worth: The Ultimate Lifetime Money Plan,' she laid out a framework that splits after-tax income into three buckets—50% for needs, 30% for wants, and 20% for savings and debt repayment, according to Investopedia. The rule's appeal is almost obvious: it's easy to remember, doesn't require spreadsheet gymnastics, and forces you to prioritize long-term financial health without turning life into a monkish exercise in denial.[3]
The Core Idea: Three Buckets, One Rule
At its heart, the 50/30/20 rule is about balance. Needs are the bills you absolutely must pay—housing, utilities, groceries, transportation, insurance, and minimum loan payments, per Investopedia and Banzai. Wants are everything else that makes life enjoyable: dining out, streaming subscriptions, that costlier steak instead of the cheaper hamburger, as Investopedia puts it. The final 20% goes to savings and extra debt repayment—building an emergency fund, contributing to retirement, or paying down credit cards beyond the minimum, according to Chase and New York Life.[3][6][2][5]
The method's power lies in its simplicity. Unlike zero-based budgeting, where every dollar must be assigned a job, or the envelope system that requires cash-stuffed envelopes, the 50/30/20 rule gives you a clear ceiling for each category without demanding meticulous tracking, notes New York Life. It also nudges you to save automatically—one of the 'great secrets to saving,' according to Banzai—by making that 20% a non-negotiable slice of your income.[5][6]
One of the great secrets to saving is finding ways to make it automatic.
When 50% Isn't Enough: High-Cost Cities and Low Incomes
The rule works best when your needs actually fit into half your income. But in expensive cities like New York or San Francisco, rent alone can swallow 40% of take-home pay, pushing needs well past 50%. The rule is a guideline, not a law, as Banzai reminds readers—and it can be adjusted. If needs exceed 50%, the fix is to trim wants and, if possible, boost income, according to Solutions Bank and SoFi. Some people may adjust the percentages temporarily, then increase savings as income grows, as suggested by Henrico HR.[6][8][9][15]
Low-income earners face a different challenge: 20% for savings might be a pipe dream when every dollar goes to rent and food. The advice from multiple sources is to start where you are. If you can't save 20%, start with 10% or even 5%, and adjust the formula accordingly—a 60-30-10 budget now, with a plan to build up to 20% over time, per Henrico HR. The key is to make savings a fixed line item, not an afterthought, because percentage-based budgets force you to pay yourself first, notes the same source.[15]
Irregular Income? Average It Out
Freelancers, gig workers, and commission-based earners often find budgeting impossible because their income swings wildly. The 50/30/20 rule has a simple answer: use an average. Albert recommends taking the average of your last six months of income, while New York Life suggests basing your budget on the rough average or the lower end of your take-home pay. This gives you a stable baseline, and in good months you can funnel the surplus into savings or debt payoff.[4][5]
Customizing for Big Goals: Debt Avalanches and Early Retirement
The 50/30/20 rule is a starting point, not a straitjacket. If you're tackling aggressive debt repayment or aiming for early retirement, you can shift more income toward savings and debt, according to NerdWallet and SoFi. The rule's flexibility is one of its strengths, as Chase notes: 'The idea behind the 50/30/20 rule is that anyone can use these proportions regardless of their income,' but you can adjust the percentages to fit your life.[14][9][3]
Pitfalls and How to Dodge Them
Critics point out that the 50/30/20 rule oversimplifies financial life. It doesn't account for irregular expenses like car repairs or medical bills, and it can be tough to categorize borderline items—is a gym membership a need or a want? The fix, according to NerdWallet, is to track your spending and adjust the percentages as needed. Also, the rule assumes you can accurately distinguish needs from wants, which is harder than it sounds. But as Banzai notes, wants are subjective and personal—the rule encourages you to be explicit about them without self-criticism.[14][8][6]
Another common pitfall is that the 20% savings category might not be enough for high earners who want to retire early, or it might be too much for someone drowning in student loans. The rule is not gospel, as Banzai puts it—it's a guideline. If you're in a debt emergency, it's fine to temporarily allocate more than 20% to debt repayment, even if that means cutting wants to the bone.[6]
Making It Stick: Practical Steps
To implement a customized 50/30/20 budget, start by calculating your after-tax income. Then, list your recurring monthly costs and your debt and savings goals, as New York Life advises. Track your spending for a month to see where you actually stand—this will reveal whether your needs are closer to 40% or 60%. From there, adjust the percentages to reflect your reality, and review the budget regularly, suggests NerdWallet. Automate your savings transfers to make the process frictionless, as UCFCU recommends.[5][14][12]
The ultimate goal, as Khan Academy puts it, is to create a balanced budget that allows you to cover your needs, enjoy life, and save for the future. The 50/30/20 rule gives you a simple, memorable framework to do that—and the flexibility to bend it when life throws you a curveball. Whether you're a freelancer in Berlin, a teacher in Nairobi, or a tech worker in San Francisco, the principle holds: pay your future first, but don't forget to live a little.[13]
Sources
- The Power of 50/30/20 Budgeting Method | Citizens State Bank — csbcolorado.com
- What Is The 50/30/20 Budget Rule? | Chase — chase.com
- The 50/30/20 Budget Rule Explained With Examples — investopedia.com
- Albert | How to Budget Your Money with the 50/30/20 Rule — albert.com
- How to Budget Using the 50 30 20 Rule | New York Life — newyorklife.com
- 50/30/20 Rule — banzai.org
- 50/30/20 Budget Calculator | Seacoast Bank — seacoastbank.com
- 50/30/20 Budget Rule: Simple Math for Smarter Money | Solutions Bank — solutions.bank
- 50/30/20 Budget Calculator | SoFi — sofi.com
- Wikipedia: Personal budget — en.wikipedia.org
- 7 Proven Financial Rules of Thumb | Johnson Financial Group — johnsonfinancialgroup.com
- What is the 50-20-20-10 Budget? — ucfcu.org
- Budgeting and the 50:30:20 rule (video) | Khan Academy — khanacademy.org
- 50/30/20 Budget Calculator - NerdWallet — nerdwallet.com
- The 50-30-20 Budget Rule Explained - Henrico HR — employees.henrico.gov
Reported with AI assistance using internet sources.